Meta has raised its 2026 capital expenditure guidance to $130B–145B while expanding its Louisiana AI campus to 5GW and backing multi-gigawatt energy agreements spanning natural gas, grid batteries, and nuclear power. While access to advanced GPUs remains vital, the physical lead time required to secure energized, high-voltage electricity has emerged as a primary binding constraint on AI scaling.
For investors, the decisive metric is no longer nominal capex or announced data center footprints, but how rapidly hyperscalers can convert capital into fully energized, operating compute capacity.
Table of Contents
Meta Platforms is scaling its artificial intelligence infrastructure at a pace unmatched in corporate history, raising its 2026 capital expenditure outlook to between $130 billion and $145 billion. Yet the most revealing aspect of Meta’s buildout is no longer the volume of silicon it purchases, but the scale of the physical energy infrastructure it is compelled to construct alongside it.
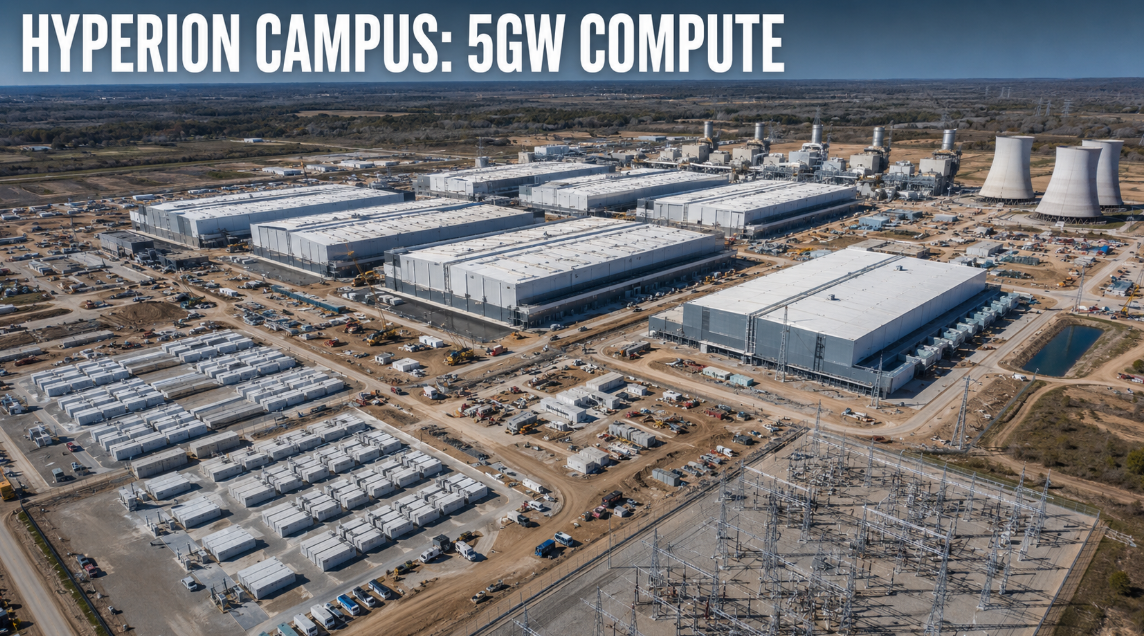
In July 2026, Meta announced an expansion of its Richland Parish data center campus in Louisiana to 5 gigawatts of compute capacity, representing more than $50 billion in total planned investment. To power the site—nicknamed Hyperion—Meta partnered with Entergy Louisiana on an energy package encompassing seven new natural gas generating units, three grid-scale battery installations, nuclear power uprates, and long-term clean power purchases. Days later, Meta finalized a $14 billion joint venture with BlackRock to develop a 1-gigawatt AI data center campus in El Paso, Texas.
The direct answer to why Meta is directly funding utility-scale generation is straightforward: electricity availability and grid interconnection timelines have become a primary binding constraint on AI growth. Securing raw GPUs is no longer the sole gating factor for hyperscale models. If a company cannot secure high-voltage power contracts and physical transmission capacity years in advance, its capital expenditures cannot convert into revenue-generating compute.
The Physical Chain Behind a Gigawatt of AI
The traditional software model assumed infrastructure could be scaled almost frictionlessly in the cloud. Frontier AI training clusters, however, operate under the rigid laws of heavy industrial engineering. Converting investment dollars into functional AI clusters requires traversing an unyielding physical sequence:
Land Acquisition → Environmental Permits → Substation & Transmission Buildout → Grid Interconnection Approval → Power Generation Sourcing → Facility Construction → Liquid Cooling Installation → Server Racking & Networking
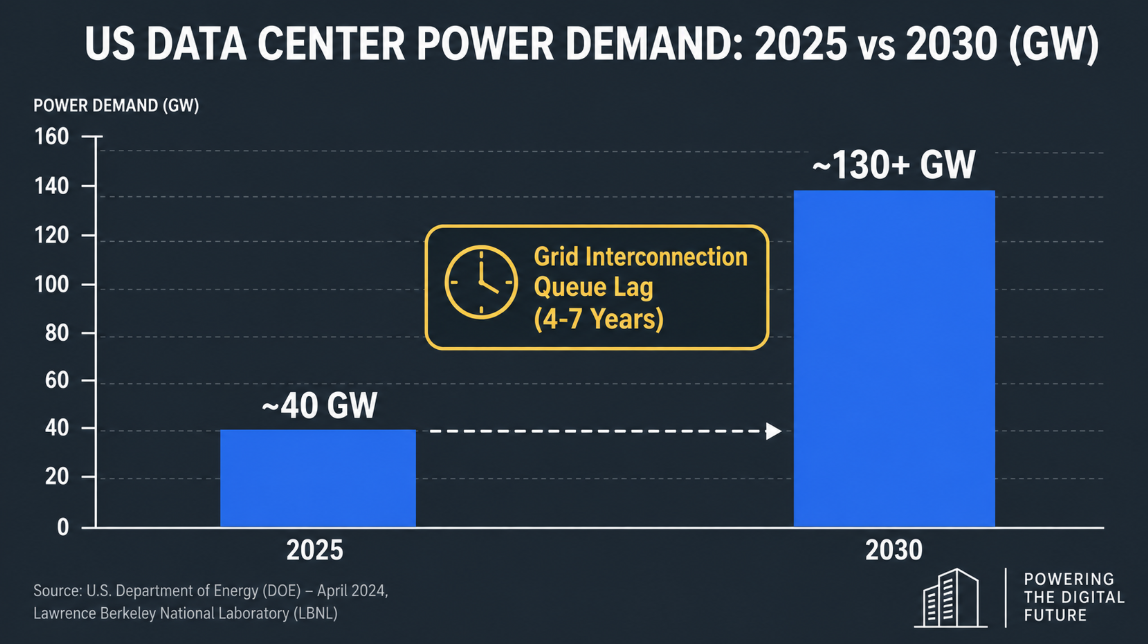
A failure or multi-year delay at any point along this chain blocks compute deployment entirely. While chip production lead times typically range from 6 to 12 months, securing transmission capacity and utility interconnection approval across major U.S. regional transmission organizations (RTOs) now frequently stretches from 4 to 7 years.
As a result, Meta is treating power not as an operational utility bill paid after the fact, but as a core strategic input that must be procured, financed, and co-developed before ground is even broken.
| Campus / Project | Compute Capacity | Estimated Investment / Structure | Primary Energy Sources | Target Online Date |
|---|---|---|---|---|
| Richland Parish (Hyperion), LA | 5.0 GW | $50B+ (Meta & Blue Owl Capital) | 7 Gas plants, 3 Grid batteries, Nuclear uprates | ~2 GW by 2030, Full by 2032 |
| El Paso Campus, TX | 1.0 GW | $14B JV (BlackRock 80% / Meta 20%) | Regional grid + El Paso Electric clean energy | 2028 initial capacity |
| Lebanon Campus, IN | 1.0 GW | $10B+ (Direct hyperscale build) | Regional MISO grid interconnection | Phased 2027–2029 |
| Nuclear Offtake Portfolio | Up to 6.6 GW | Long-term PPAs & development funding | Vistra (conventional), Oklo & TerraPower (SMRs) | 2026–2035 |
Why Meta Is Structuring a Multi-Decade Power Portfolio
Meta’s procurement strategy reveals a deliberate bifurcation between near-term grid pragmatism and long-term baseload hedging.
For capacity needed between 2026 and 2029, Meta is heavily relying on natural gas peakers, existing nuclear capacity, and large-scale battery storage. In Louisiana, the addition of combined-cycle natural gas units provides Entergy with the dispatchable capacity required to stabilize local grid frequencies under the massive, volatile load swings characteristic of large-scale AI model training.
Simultaneously, Meta is positioning itself for the 2030s by executing agreements with advanced nuclear developers:
- Vistra Corp: Securing long-term power purchase agreements from existing commercial nuclear reactors alongside planned capacity uprates.
- Oklo Inc.: Development funding and power agreements targeting up to 1.2 gigawatts of small modular reactor (SMR) capacity, with initial deployments aimed for 2030.
- TerraPower: Backing advanced Natrium sodium-cooled fast reactor installations designed to deliver up to 2.8 gigawatts of carbon-free baseload power by 2032 and beyond.
This staggered approach proves that Meta does not view nuclear energy as a quick fix for today's bottlenecks, but as the foundational baseload necessary to sustain exponential model growth into the next decade.
Announced Capacity vs. Energized Capacity
A critical analytical error in current market analysis is conflating announced data center gigawatts with energized, operational compute.
Grid operators like PJM Interconnection and MISO are facing unprecedented interconnection queues. While regional demand forecasts have surged, grid operators have begun tightening review processes to weed out speculative data center interconnection requests.
| Power Source Category | Typical Development Lead Time | Deployment Role for Meta | Key Execution Risk |
|---|---|---|---|
| Natural Gas Generation & Storage | 2 to 4 Years | Immediate baseload & ramping bridge (2026–2029) | Pipeline permitting & local emissions limits |
| Existing Nuclear Offtake & Uprates | 1 to 3 Years | Near-term zero-carbon baseload | Regulatory approvals & high procurement premiums |
| Small Modular Reactors (SMRs) | 6 to 10+ Years | Long-term structural power supply (2030–2035+) | First-of-a-kind licensing & NRC approval delays |
When evaluating Meta’s $130B–$145B annual capex run rate, the risk is not that Meta lacks cash flow, but that capital committed to physical shells may sit underutilized if substation transformers, transmission lines, or utility generation units suffer commissioning delays.
Countervailing Forces: Is Power Truly the Only Constraint?
To maintain analytical rigor, investors must weigh the counterarguments to the power bottleneck thesis:
- Algorithmic & Inference Efficiency: Advances in quantization, speculative decoding, and model architecture (e.g., smaller specialized models outperforming dense parameter giants) could dramatically reduce the energy required per inference query.
- Capital Flexibility via Joint Ventures: Meta’s $14 billion structure with BlackRock in El Paso demonstrates that hyperscalers can offload balance-sheet real estate and infrastructure obligations to institutional infrastructure funds, preserving capital for core research.
- Distributed Training Across Clusters: If optical interconnects and distributed training architectures advance to allow low-latency model training across geographically separated sites, the requirement for single-site 5GW mega-campuses may soften.
Nevertheless, while efficiency gains reduce the energy required per token, the Jevons Paradox suggests that lower inference costs will exponentially expand total enterprise adoption, keeping aggregate gross energy demand steep.
The Investor Decision Rule: Tracking Energization Over Announcements
Power is not the sole variable governing the AI race, but it has officially graduated from a secondary facility expense to a defining operational constraint. Hyperscalers that master long-duration utility partnerships, innovative off-balance-sheet financing, and diverse energy sourcing will convert their capital expenditures into usable computing clusters significantly faster than competitors reliant solely on standard grid queues.
What to Watch Next:
- Energization Milestones: Track the commercial operation dates of Entergy’s planned gas units in Louisiana and substation completions at the El Paso campus, rather than nominal real estate groundbreaking.
- Capex-to-Compute Conversion Efficiency: Monitor Meta’s infrastructure depreciation schedule versus active family-of-apps AI query capacity in quarterly SEC filings.
- SMR Regulatory Filings: Watch for NRC design certifications and site permit approvals for Oklo and TerraPower projects scheduled for late-decade deployment.
Foundayo Costs a Fraction of Mounjaro. Is Eli Lilly Expanding the Market or Cannibalizing It?
Foundayo Costs a Fraction of Mounjaro. Is Eli Lilly Expanding the Market or Cannibalizing It?
더보기Eli Lilly’s oral GLP-1 Foundayo enters the market at a fraction of Mounjaro’s price. Discover whether this pill expands the obesity market or risks cannibalizing premium injections. Eli Lilly’s newly approved oral GLP-1, Foundayo (orforglipr
global.kkomccom.com
Did Google Just Hand Marvell $120 Billion? What the Filing Actually Says
Did Google Just Hand Marvell $120 Billion? What the Filing Actually Says
더보기Google did not hand Marvell $12.2B in cash, and Marvell has $0 in guaranteed revenue. Here is what the SEC Form 8-K warrant deal actually proves.Financial headlines went wild over Google’s "$120 billion AI chip deal" and "$12.2 billion Marvell s
global.kkomccom.com